The Fall Strategic Focus: Buying Beyond the Purchase Price in South Metro Atlanta
The Fall Strategic Focus: Buying Beyond the Purchase Price
Fixating on a home's sticker price alone is one of the easiest ways to blow past your actual budget.
As we move into late September, taking a strategic look at your total out-of-pocket closing cash, true monthly housing expenses, and multi-year lifestyle adaptability can help ensure you purchase a home that fits both your current lifestyle and long-term financial goals.
A $350,000 home isn't automatically more affordable than a $365,000 home.
And a home that's comfortably within your preapproval amount isn't automatically comfortably within your budget.
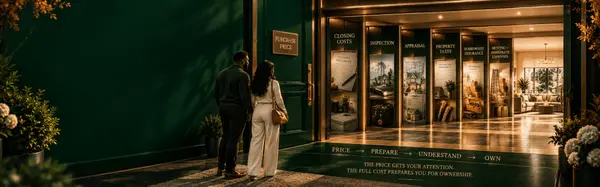
That's because the purchase price is only one dimension of the homebuying decision.
Before you fall in love with the kitchen, backyard or primary suite, there are three numbers—or, more accurately, three strategic categories—I want you to understand:
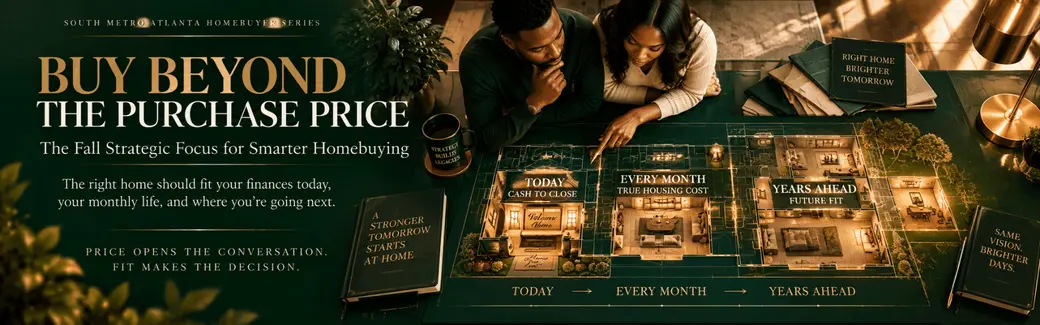
Cash to Close → True Monthly Cost → Future Fit
Let's break them down.
1. Know Your Total Cash to Close—Not Just Your Down Payment
One of the biggest surprises for buyers happens when they begin the process thinking:
“I have my down payment saved, so I'm ready.”
Your down payment is important, but it isn't necessarily the only cash you'll need throughout the transaction.
Depending on your loan, contract and property, your overall homebuying expenses may include your down payment, closing costs, prepaid expenses, inspections, appraisal-related expenses, moving costs and other transaction-specific items.
There may also be earnest money paid earlier in the transaction that is later credited as provided by the contract and closing statement.
The goal is to understand your entire cash position, not one number.
Don't Empty the Bank Account to Get the Keys
Suppose you technically have enough money to close—but doing so would leave you with almost nothing afterward.
What happens if the HVAC needs service two months later?
What if you discover you need a refrigerator, blinds, lawn equipment or another immediate household expense?
What if life simply happens?
Getting through closing shouldn't be the only financial objective.
You also want to be financially prepared for the morning after closing.
That's why I encourage buyers to discuss three separate numbers with their lender:
How much cash do I need to close?
How much cash will I have remaining after closing?
What amount am I personally comfortable keeping in reserve?
That last number isn't about what your lender says you can spend.
It's about what helps you sleep comfortably at night.
2. Calculate Your True Monthly Housing Expense
The second mistake buyers make is looking at a mortgage principal-and-interest estimate and calling it their “house payment.”
Those aren't necessarily the same thing.
Your actual monthly housing obligation can include:
- Principal and interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, when applicable
- HOA dues, when applicable
And your household budget also needs room for utilities, maintenance, repairs and the ongoing costs of owning the particular property you choose.
This becomes especially important when comparing two houses.
Imagine one home has a lower purchase price but higher ongoing expenses.
Another costs slightly more but fits your household differently.
The listing price alone doesn't tell you which one fits your budget better.
Ask About Payment Before You Ask About Price
When I work with buyers, I don't want the conversation to stop at:
“What's your maximum purchase price?”
I want to know:
“What monthly housing expense feels comfortable for your life?”
There's a significant difference.
Your lender's job is to determine what financing you qualify for under the loan program.
Your job is to determine what you actually want to spend.
Those two numbers don't have to be identical.
Preapproval gives you a financing ceiling. Your personal budget should give you a comfort zone.
3. Remember That Property Taxes Can Change the Numbers
Property taxes deserve particular attention because buyers sometimes look at what the current homeowner is paying and assume their future tax bill will be identical.
Don't automatically make that assumption.
Property taxes can depend on factors involving assessed value, exemptions, ownership circumstances, taxing jurisdiction and other local rules.
This is particularly important when comparing homes across South Metro Atlanta.
Before making a decision based on a seller's existing tax bill, talk with the appropriate professionals and local taxing authority about how the property may be treated after the transaction.
The same principle applies to insurance.
Two homes at similar prices can produce different insurance costs based on the property and insurer.
The house price tells you what you're buying. The monthly numbers help tell you what you're committing to.
4. HOA Costs—and HOA Rules—Belong in the Budget Conversation
If the property has a homeowners association, don't treat the HOA as an afterthought.
Understand the current dues and review the available governing documents and disclosures applicable to the transaction.
But I also want buyers to think beyond the fee.
Does the community fit how you intend to use the property?
If you expect to park certain vehicles, add improvements, fence the yard, operate within particular rental rules, or make exterior modifications, applicable HOA restrictions can matter.
Your due diligence should therefore answer two different questions:
Can I afford the community?
And:
Does the community fit the way I want to live?
5. Think About the House Three to Five Years From Now
Now we get to the part buyers frequently overlook:
Multi-year adaptability.
A home can be perfect for your life today and frustrating two years from now.
Before buying, consider what your life could reasonably look like several years into ownership.
Maybe you're working remotely more often.
Maybe aging parents could eventually live with you.
Maybe your children are getting older and need different space.
Maybe you're planning to have children.
Perhaps you need a dedicated office.
Maybe a main-level bedroom would become increasingly valuable.
Perhaps you're downsizing and want to reduce stairs.
Or maybe you're buying your first home but already know this probably won't be your last.
You can't predict everything.
You don't need to.
You're simply asking:
“Does this home give my life room to change?”
6. Floor Plan Can Matter More Than Finishes
This is one reason I talk so much about functional floor plans with my buyers.
Beautiful countertops can be changed.
Paint can be changed.
Light fixtures can be changed.
Flooring can be changed.
Changing an awkward floor plan may be much more complicated and expensive.
When you're walking through a property, don't only ask:
“Do I like this room?”
Ask:
“How many ways could this room work for me?”
A flex room might become an office today and guest space later.
A main-level bedroom could serve guests now and potentially support multigenerational living later.
A bonus room could evolve as your household changes.
Storage may not photograph beautifully on a listing, but it can significantly affect day-to-day functionality.
Buy for today's life—but evaluate for tomorrow's possibilities.
7. Separate “I Love It” From “It Works”
This can be difficult.
You walk into a home.
The lighting is perfect.
The furniture is beautiful.
The kitchen looks like something you saved on Pinterest six months ago.
Then emotion takes over.
There's nothing wrong with loving a house.
Real estate is both a financial and emotional decision.
But emotion shouldn't eliminate analysis.
Before writing the offer, come back to your three-part framework:
Cash to Close
After closing, do I still have a financial cushion I'm comfortable with?
True Monthly Cost
Does the complete housing expense fit comfortably into my actual monthly life?
Future Fit
Does the home give me enough flexibility for the next chapter?
If you can answer those questions confidently, now we're evaluating more than a beautiful house.
We're evaluating whether it's a strategic purchase.
8. Don't Confuse “Approved” With “Affordable”
This deserves its own conversation.
Suppose your lender preapproves you up to a certain purchase price.
That number tells us something important about financing.
But it doesn't know everything about your life.
Your lender doesn't determine how much you want to spend on travel.
Or how aggressively you want to save for retirement.
Or what you're contributing toward college.
Or how much you give.
Or what other personal financial priorities matter to you.
So don't automatically turn your maximum approval into your target purchase price.
You might be approved up to one number and intentionally shop below it.
That's not failing to maximize your buying power.
It may be protecting your lifestyle.
9. Seller Concessions Can Be Part of the Bigger Strategy
Purchase price also isn't the only thing we may evaluate when negotiating.
Depending on the property, seller, market conditions, loan program and terms of the transaction, negotiations can potentially involve items such as:
Seller concessions
Eligible closing-cost assistance
Repairs
Closing timeline
Certain temporary or permanent rate-buydown costs
The point isn't that sellers will automatically agree to these requests.
They may not.
The point is that sophisticated negotiation considers the whole transaction, not simply how much money can be removed from the purchase price.
For example, a buyer who needs to preserve cash might value an allowable seller contribution differently from a buyer whose primary objective is reducing the price.
That's why your real estate agent and lender should be communicating before you submit the offer.
10. The Cheapest House Isn't Always the Most Affordable House
This distinction is important.
Price and affordability are related—but they're not identical.
A less expensive house that requires substantial immediate repairs could place more pressure on your finances.
A home with a manageable purchase price but uncomfortable monthly carrying costs could create long-term stress.
A beautifully priced home that doesn't support your household's needs might force another move sooner than expected.
Conversely, paying more doesn't automatically make another home the better choice.
That's why we evaluate.
We don't simply chase the lowest number.
Your Fall Homebuying Strategy: Think in Three Dimensions
As you tour homes this fall in Henry County and South Metro Atlanta, I want you to stop looking at the price as the entire decision.
Instead, imagine every property through three lenses:
TODAY — Cash to Close
What will it take financially to get through the front door?
EVERY MONTH — True Housing Cost
What will owning this property realistically require from your household budget?
YEARS AHEAD — Future Fit
Can the property continue supporting your lifestyle as your needs evolve?
That's a much stronger homebuying conversation than:
“What's the list price?”
Because the objective isn't simply to buy a home.
It's to buy a home you can comfortably own, maintain and live in.
The Fall Strategic Focus
Fall can be a useful time to recalibrate your search.
Maybe you spent the summer chasing homes based primarily on price.
Maybe you've been waiting for rates to change.
Maybe your preapproval came back higher than you expected and you're tempted to stretch.
Or perhaps you've been looking at so many listings that you've lost sight of what you actually need.
This is your opportunity to reset the strategy.
Before the next showing, write down these three numbers and questions:
1. CASH: How much am I comfortable spending to close while maintaining my desired reserves?
2. MONTHLY: What complete monthly housing expense fits comfortably into my lifestyle?
3. FUTURE: What does this home need to provide so I don't immediately outgrow it?
Now your search has boundaries.
And boundaries make it easier to recognize the right opportunity when you see it.
FAQs
What costs should I consider besides the purchase price of a home?
Depending on your transaction, consider the down payment, closing costs, prepaid expenses, inspection and appraisal-related expenses, moving costs and money you want available after closing. For your ongoing budget, consider the full housing payment plus utilities, maintenance and future repairs.
Is my preapproval amount the same as my homebuying budget?
Not necessarily. A preapproval is based on lending criteria. Your personal budget should also account for your lifestyle, savings goals, other financial obligations and the monthly payment you're comfortable carrying.
Should I buy below my maximum preapproval?
That is a personal financial decision. Some buyers intentionally purchase below their maximum financing eligibility because doing so better supports their monthly budget, savings goals or lifestyle.
Should I rely on the seller's current property-tax bill?
Don't assume the seller's current tax amount will automatically become yours. Property taxes can be affected by assessments, exemptions and other factors. Verify property-specific information with the appropriate professionals and local taxing authority.
Should I choose a house based on monthly payment instead of price?
Consider both. The purchase price matters, but your full monthly housing expense, upfront cash requirement, property condition and long-term suitability also deserve consideration.
Can seller concessions help with affordability?
Potentially. Depending on your financing, transaction and seller agreement, allowable concessions may help with eligible closing expenses or certain financing costs. Your lender should confirm what is permitted for your specific loan.
Don't shop for the biggest mortgage you can qualify for. Shop for the home that fits the life you're building.
If you're preparing to buy in Henry County or South Metro Atlanta, let's build your home search around more than the listing price.
We'll look at your cash-to-close strategy, comfortable monthly housing budget, lifestyle priorities, future needs and negotiation opportunities so you can evaluate each home through a clearer lens.
Contact Natasha Ewing Johnson today to schedule your complimentary Homebuyer Strategy Call.
Move Strategically. Live Abundantly.
This article is for general educational purposes and is not financial, tax, legal, insurance or lending advice. Costs, financing requirements, taxes, insurance, HOA obligations and transaction terms vary by property and buyer. Consult the appropriate licensed professionals for advice specific to your situation.
Categories
Recent Posts